When Globus closed the NuVasive deal in September 2023, plenty of people in the industry, including many on Wall Street, doubted whether it would work. The companies had very different cultures, their sales forces had spent years competing head-to-head, and the spine sector had a long history of mergers that destroyed rather than created value.
Three years later, most of those doubts have faded, and the market looks very different. Spine is no longer a crowded field with Medtronic clearly out in front. It has become a two-horse race, with everyone else now working out where they fit.
By industry estimates that count spine implants only, Medtronic and Globus each booked more than $2 billion last year, giving them close to 43% of the global market between them. The next company down the list has no more than 8%. That leaves Globus much closer to Medtronic than to anyone chasing it from behind, something that would have been hard to imagine before the merger.
Has Globus already overtaken Medtronic?
Not quite, at least based on the numbers we can piece together. Neither company reports a clean spine revenue figure, so any comparison involves some estimation. We tried to compare like with like: spine implants plus the navigation and robotics sold alongside them.
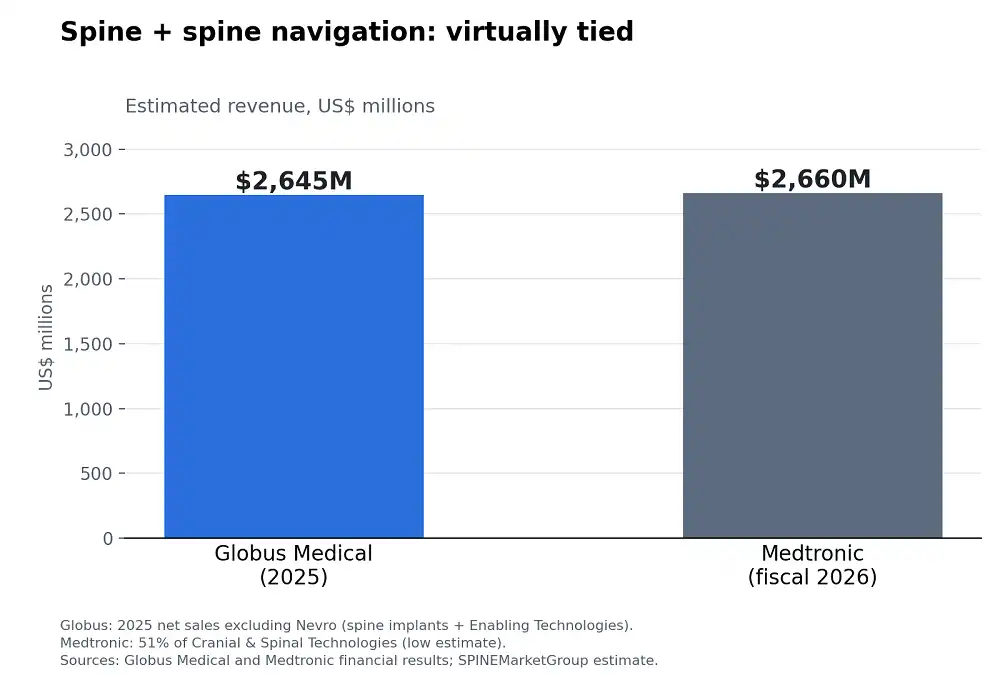
For Globus, we used reported 2025 net sales excluding Nevro of $2,645 million. That includes roughly $2,504 million in implants and $141 million in Enabling Technologies, mostly ExcelsiusGPS, ExcelsiusHub and Excelsius3D. The implant number still contains some trauma and knee revenue, so Globus’s pure spine business is somewhat smaller.
For Medtronic, we took 51% of the $5,220 million booked by its Cranial & Spinal Technologies division in fiscal 2026, broadly in line with spine’s historical weight within the business. That also captures the share of StealthStation, O-arm and Mazor used in spine procedures. Some industry estimates put spine closer to 60% of the division, which would leave Medtronic with a more meaningful lead. The reporting periods do not line up perfectly either: Globus reports on the calendar year, while Medtronic’s fiscal 2026 ended in April.
On our assumptions, the difference between the two companies is only around $15 million, or roughly 0.6%. Given the limitations of the data, that number should not be taken too literally. The more useful conclusion is that the two businesses are now effectively neck and neck.
What matters more is momentum. In Q2 2026, Globus grew U.S. Spine 7% and International Spine 12% at constant currency, and U.S. Spine has now outgrown the market for five consecutive quarters. Medtronic’s Cranial & Spinal Technologies division grew around 5% in its last fiscal year, while the broader spine market expanded by roughly 3% in 2025.
When will Globus overtake Medtronic?
If the current gap is as small as it appears, Globus does not need much more share to move ahead. Whether that happens in 2026, 2027 or later will depend on several things.
- The first is robots. Enabling Technologies revenue fell 26% in Q2 as Globus shifted more customers toward leases and rentals, but placements of ExcelsiusGPS and ExcelsiusHub increased 25% year over year. The upfront revenue from the robot is only part of the equation. What matters more is the implant volume it can pull through over the years that follow.
- The second is people. CEO Keith Pfeil has made clear that competitive recruiting will remain central to the company’s strategy. In spine, business still tends to follow the rep, and Globus has been one of the industry’s most aggressive recruiters.
- The third is international. Medtronic’s global footprint remains one of its biggest structural advantages. Globus has been growing quickly outside the U.S., but narrowing that gap will require sustained double-digit growth over several years. A few strong quarters will not be enough.
- Then there is Nevro. It is still weighing on reported growth and consuming management attention at a time when the competition in spine is becoming more intense.
Why the ecosystem matters
The competition is about much more than screws, cages and biologics. It is increasingly about controlling more of the operating room: navigation, robotics, imaging and implants sold as an integrated system. Without that kind of ecosystem, it is becoming very difficult to compete for leadership in spine. Both Medtronic and Globus use enabling technology to deepen relationships with their most important accounts, and the battle for first place will ultimately be decided hospital by hospital.
Medtronic has not been standing still. Stealth AXiS, cleared by the FDA in February and CE marked in April, brings planning, navigation and robotics together in a single platform and is the company’s clearest answer yet to the Excelsius ecosystem.
The big orthopedic names step back
While Medtronic and Globus were building those ecosystems, several diversified orthopedic companies were heading in the opposite direction. Stryker sold its spine implant business to the Viscogliosi Brothers, who launched VB Spine in April 2025. Zimmer Biomet had already spun off ZimVie, which later sold its spine business to H.I.G. Capital, where it became Highridge Medical. Neither company described enabling technology as the reason for leaving spine, but competing at the top end of the market increasingly requires investment in robotics, navigation, imaging and the infrastructure around them, as well as implants.
J&J may be the next major name to change course. It announced plans to separate DePuy Synthes in October 2025, and in September the Wall Street Journal and Bloomberg reported that it was in talks with Apollo over a transaction worth around $20 billion. If DePuy ends up under private equity ownership, its strategy in spine will draw a lot of attention. A focus on cash generation and margins would look very different from the level of investment required to challenge Medtronic and Globus in enabling technology. Globus and Medtronic will both be watching closely.
What comes next
Below the top two sits a long and highly competitive mid-tier. ATEC is the clearest growth story: revenue increased 25% to $764 million in 2025, and the company has guided to around $890 million for 2026. DePuy Synthes Spine, at close to $900 million by industry estimates, remains a large business even after years of share losses.
Behind them are companies that have built strong positions around particular procedures, technologies or surgeon groups. Orthofix, VB Spine and Highridge Medical offer broad portfolios. SI-BONE leads in SI joint fusion, while Centinel Spine is a major player in total disc replacement. Carlsmed is growing quickly in personalized implants, and a long group of smaller U.S. and European companies continues to compete through focused portfolios and distributor networks.
ATEC has shown that a focused company can still take meaningful share. What none of these businesses has yet is the combination of scale, full-line implants, enabling technology and global reach that Medtronic and Globus can bring to the same account. That is why more consolidation still looks likely, and the outcome of the DePuy process could accelerate it.
Hospitals may ultimately have fewer full-line suppliers to play against each other on price, while experienced spine reps will increasingly find two companies competing hardest for their business. For Medtronic, that creates a position it has not faced in a very long time. It is still number one in spine. But not by much.
###
Legal Disclaimer:
Content published on SPINEMarketGroup (thespinemarketgroup.com) is provided for informational purposes only and on an “as is” basis, without warranties of any kind. We do not guarantee the accuracy, completeness, legality, or reliability of any information, images, videos, links, or third-party materials featured on the site. Any views or claims expressed in contributed content or press releases belong to their respective authors or sources. For copyright concerns, factual corrections, or content-related complaints, please contact us directly for review.